
EXECUTIVE SUMMARY
In an era hyper-fixated on productivity metrics, algorithmic optimization, and the relentless pursuit of efficiency, modern professionals are continually urged to work smarter, not harder. Central to this philosophy is the 80/20 Rule—the Pareto Principle—which dictates that a minority of inputs drive the majority of outputs. It is a powerful heuristic for separating the vital few from the trivial many, helping corporations, entrepreneurs, and creatives maximize their existing skill sets.
However, a meticulous examination of history reveals a critical, often-overlooked blind spot in this framework: the 80/20 Rule is entirely backward-looking. By relying on historical data to calculate the "highest and best use" of time, optimization models inherently favor past achievements over future transformations.
This investigative piece examines the hidden trap of hyper-effectiveness through the lives of cultural icons like Audrey Hepburn and business titans like Jeff Bezos. By analyzing how radical career pivots defy conventional economic and productivity logic, we explore why the most meaningful pursuits often register as catastrophic inefficiencies at their inception—and how true reinvention requires unlearning the very metrics that brought us initial success.
1. Executive Overview: The Tyranny of Past Performance
For decades, productivity gurus and management consultants have preached the gospel of effectiveness. While efficiency is concerned with doing things right, effectiveness is about doing the right things. Management pioneer Peter Drucker famously captured this sentiment: "There is nothing so useless as doing efficiently that which should not be done at all."
To isolate these high-leverage activities, decision-makers universally turn to the Pareto Principle. Named after Italian economist Vilfredo Pareto—who observed in 1896 that 80% of Italy’s land was owned by 20% of its population—the principle manifests across nearly every domain of human endeavor. In business, 80% of revenue typically comes from 20% of clients. In sports, a small fraction of teams capture the vast majority of championships.
Yet, when applied to personal career trajectories and long-term life design, the Pareto Principle contains a subtle, paralyzing trap. Because the 80/20 Rule is calculated using recent effectiveness and established capabilities, it inherently optimizes an individual’s past rather than their future.
When a person is operating at the absolute peak of their profession, any analytical framework grounded in historical data will advise them to double down on what they already do best. But what happens when an individual no longer wants their future to look like their past? As history demonstrates, stepping away from guaranteed optimization is the prerequisite for transcendent impact.
2. Detailed Chronology: The Audacious Exits of Hepburn and Bezos
To understand the friction between optimization and reinvention, one must examine the turning points in the lives of individuals who walked away from guaranteed preeminence.
The Rise and Transformation of Audrey Hepburn
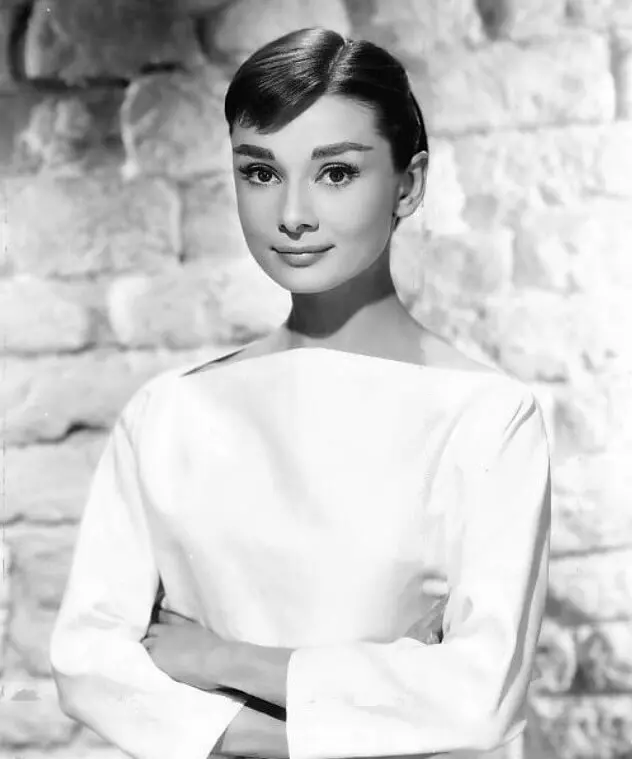
By 1967, Audrey Hepburn was undisputed cinematic royalty. Rising to international prominence in the early 1950s, she achieved a milestone in 1953 by becoming the first actress to win an Academy Award, a Golden Globe Award, and a BAFTA Award simultaneously for a single leading performance in the romantic comedy Roman Holiday.
Her cultural footprint expanded rapidly over the next decade and a half. Starring in a string of critical and commercial triumphs—including Sabrina (1954), Breakfast at Tiffany’s (1961), and Charade (1963)—she maintained a relentless production schedule. By the mid-1960s, she was averaging more than one major motion picture per year. She was on a trajectory to remain a dominant cinematic force for decades, securing wealth, global adoration, and critical acclaim.
Then, at the height of her powers in her late 30s, Hepburn enacted a near-total cessation of her acting career. Aside from a sparse handful of television and film appearances over the next twenty-five years, she vanished from the silver screen.
Her new arena was not Hollywood studios, but the dirt roads of war-torn and impoverished regions across Africa, South America, and Asia. As a Goodwill Ambassador for UNICEF, Hepburn spent the remainder of her life advocating for children suffering from malnutrition, preventable disease, and geopolitical conflict.
In December 1992, her decades of humanitarian labor culminated when she was posthumously awarded the Presidential Medal of Freedom—the highest civilian honor in the United States. It was an accolade she never could have secured by continuing to star in romantic comedies.
Jeff Bezos and the 1993 Wall Street Exodus
A parallel narrative unfolded decades later in the financial sector. By 1993, Jeff Bezos had climbed the corporate ladder on Wall Street, ultimately serving as senior vice president for the quantitative hedge fund D.E. Shaw & Co. He was exceptionally effective by every traditional metric of the financial elite: high compensation, immense social capital, and a clear pathway to permanent institutional power.
Had Bezos applied an 80/20 analysis to his career prospects in 1993, quantitative models would have overwhelmingly dictated that he remain in finance. The internet was in its nascent infancy, e-commerce was entirely unproven, and abandoning a lucrative hedge fund career for a digital bookstore carried a near-certain probability of professional and financial failure.
Yet, utilizing a decision-making framework based on minimizing future regret rather than maximizing current efficiency, Bezos walked away from Wall Street to found Amazon in a Bellevue, Washington garage.
3. Supporting Context & Metrics: The Mathematics of Inefficiency
To rigorously evaluate why traditional productivity frameworks fail during periods of transition, we must examine the underlying mechanics of how human capital is valued and deployed.
The Blind Spot of Quantitative Heuristics
Quantitative decision-making models—including the Pareto Principle, return on investment (ROI) calculations, and opportunity cost analyses—rely exclusively on established datasets. They measure:
- Marginal returns on invested time: How much revenue or acclaim is generated per hour of labor within a known discipline.
- Skill leverage: The degree to which existing neural pathways and muscle memory reduce friction in task execution.
- Risk mitigation: The historical predictability of outcomes based on accumulated experience.
When an individual is an elite practitioner—whether as an Academy Award-winning actress or a top-tier quantitative financier—their marginal return on time within that specific domain is astronomically high. Consequently, any quantitative model views a departure from that domain as an irrational allocation of resources.
The Cost of Mastery in a New Domain
When Hepburn transitioned to humanitarian work in 1967, or when Bezos began shipping books out of a garage in 1994, they experienced an immediate, precipitous drop in functional efficiency.
- The Learning Curve Penalty: In any new domain, an expert instantly becomes a novice. The cognitive load required to navigate unfamiliar bureaucratic structures, international relief protocols, or supply chain logistics yields virtually zero immediate output compared to decades of refined artistic or financial performance.
- The Inefficiency Paradox: For the first several years of a radical pivot, the new endeavor will perpetually fail an 80/20 analysis. It consumes 80% of an individual’s cognitive and emotional energy while generating a negligible fraction of their historical output, prestige, or income.
4. Official Perspectives and Expert Analysis
Management theorists and behavioral psychologists have increasingly turned their attention to the dangers of hyper-optimization in modern career design.
Dr. Carol Dweck, a leading psychologist at Stanford University renowned for her work on fixed versus growth mindsets, notes that individuals trapped in systems of high historical success often develop an aversion to appearing incompetent.
"When you are accustomed to being at the top of your field, the ego threat of starting over at the bottom is immense," explains institutional strategist Marcus Vance. "Most people choose the comfort of optimized irrelevance over the acute discomfort of foundational incompetence."
Economists studying long-term career trajectories emphasize the concept of "path dependency"—the idea that decisions made in the past limit future choices. When professionals rely exclusively on the Pareto Principle to prune their daily schedules, they inadvertently reinforce their path dependency. They become exceptionally skilled at iterating on what already exists, insulating themselves from the disruptive mutations required for generational impact.
As Peter Drucker himself frequently cautioned, efficiency is concerned with doing things right, but leadership is about doing the right things—and identifying the "right thing" often requires stepping outside the boundaries of historical data altogether.
5. Future Outlook: Reimagining Personal Productivity for the Long Term
As artificial intelligence and automated systems increasingly absorb tasks governed by efficiency and optimization, the human mandate is shifting. Machines will execute the 80/20 rule faster and more comprehensively than any human analyst.
Consequently, the future belongs not to those who optimize their past, but to those who possess the courage to embrace strategic inefficiency.
Strategic Recommendations for Navigating Career Pivots
- Accept the Inefficiency Penalty: Acknowledge that any meaningful transition into a new domain will temporarily tank your productivity metrics. Treat this not as a failure of execution, but as the mandatory cost of entry into a new paradigm.
- Audit for Regret, Not Just Return: When evaluating major life decisions, utilize mental models such as Jeff Bezos’s "Regret Minimization Framework." Ask yourself not what yields the highest immediate return today, but what path leaves you unfulfilled decades from now if left unexplored.
- Deliberate Practice over Marginal Gains: Understand that you get good at what you practice. If you spend your life optimizing your past skills, you will guarantee a future composed entirely of your previous iterations.
Audrey Hepburn did not change the world by calculating where her acting skills would yield the highest marginal return. She changed the world by stepping away from the stage entirely, enduring the difficult descent from global icon to novice humanitarian, and mastering a completely new craft over three decades of tireless service.
True innovation does not live in the top 20% of your past. It waits in the inefficient, uncertain margins of your future.