
By Financial News Desk
Published September 16, 2026
Executive Overview
In a decisive move that marks a major turning point for the U.S. economy, the Federal Reserve has officially broken a three-year monetary policy pause. On Wednesday, the Federal Open Market Committee (FOMC) voted unanimously to raise the benchmark interest rate by a quarter of a percentage point, pushing the federal funds rate to a target range of 3.75% to 4%.
This adjustment—the first of its kind since July 2023—signals an aggressive renewed stance by central bank leadership against stubborn price growth. Newly confirmed Federal Reserve Chair Kevin Warsh, spearheading his first major policy decision, emphasized that the central bank could no longer stand idly by as cost-of-living metrics outpaced target stabilization goals.
While financial markets had largely anticipated a shift in monetary policy, the practical implications for everyday consumers, prospective homebuyers, and corporate borrowers are profound. As the era of ultra-low borrowing costs fades further into memory, individuals across the nation must navigate an increasingly expensive financial landscape. From fluctuating variable-rate mortgages and higher monthly auto payments to climbing credit card APRs and incrementally better returns for savers, the ripple effects of Wednesday’s announcement will be felt across every corner of personal finance.
Detailed Chronology: The Road to the September 2026 Rate Hike
To understand the significance of Wednesday’s policy shift, it is essential to trace the economic trajectory that brought the Federal Reserve to this juncture.
The Post-Pandemic Inflation Shock and Peak Rates (2022–2023)
In the wake of unprecedented fiscal stimulus and global supply chain disruptions following the COVID-19 pandemic, inflation soared to multi-decade highs in 2022. To combat runaway consumer prices, the Fed embarked on one of the most aggressive tightening cycles in its history, rapidly escalating the benchmark rate from near-zero to a restrictive plateau between 5.25% and 5.50% by mid-2023.
The Great Pause (Late 2023–Mid 2026)
By July 2023, the central bank opted to pause further rate increases, maintaining a holding pattern as economic indicators flashed mixed signals. For nearly three years, policymakers kept rates steady, hoping that prior hikes would sufficiently cool the economy without triggering a hard landing or a deep recession. During this prolonged plateau, consumer borrowing costs stabilized at elevated levels, while the stock market experienced considerable volatility and subsequent recoveries.
Leadership Transition and the Pivot to Action (Summer–September 2026)
The political and institutional landscape of the central bank shifted earlier this year with the Senate confirmation of Kevin Warsh as Federal Reserve Chair. Tasked with navigating lingering inflationary pressures and a shifting labor market, Warsh and the FOMC faced mounting pressure from economic data showing that inflation had stalled well above the Fed’s coveted 2% target.
The unanimous 12-0 vote on Wednesday was the culmination of months of internal consensus building. Recognizing that inflation expectations risked becoming unmoored, the FOMC enacted the quarter-point hike, signaling to markets that the central bank remains vigilant and unhesitating in its mandate to restore price stability.
Supporting Context & Metrics: What the Hike Means for Your Wallet
The practical fallout of a Federal Reserve rate hike is rarely uniform. Its impact ripples through various financial products at different speeds, depending on whether a borrower is locked into fixed terms or exposed to variable market mechanics.
Mortgages: Fixed vs. Variable Realities
For homeowners currently holding a fixed-rate mortgage, Wednesday’s announcement changes nothing. Existing fixed loans remain locked in at their original rates for the life of the loan, shielding borrowers from macroeconomic shifts.
However, prospective buyers and those with adjustable-rate mortgages (ARMs) face a vastly different reality. Mortgage rates are not directly set by the Federal Reserve; instead, they track closely with long-term macroeconomic indicators, most notably the yield on 10-year Treasury bonds. Recently, Treasury yields topped 5% for the first time since 2023, propelling the average 30-year fixed mortgage rate to 6.76%, according to data compiled by The Washington Post. This dual pressure—rising underlying bond yields and the Fed’s baseline rate hike—means purchasing a home has become significantly more expensive than it was just a few years ago.
Auto Loans and Consumer Credit
The automotive sector is bracing for immediate headwinds. Cox Automotive estimates that the quarter-point increase will tack an additional $6 onto the average monthly car payment for new buyers. While seemingly modest on paper, compounded across multi-year financing terms and combined with elevated vehicle sticker prices and insurance premiums, this increase adds meaningful friction to household budgets.
Meanwhile, credit cards—which are notoriously sensitive to federal benchmark adjustments—are expected to see APRs tick even higher. This development arrives at a precarious time for American consumers, with nationwide credit card debt hovering near historic all-time highs. Financial advisors warn that carrying balances through this tightening cycle will become exponentially more expensive, compounding debt traps for vulnerable households.
A Silver Lining for Savers
It is not all bad news. For individuals holding cash reserves, high-yield savings accounts, certificates of deposit (CDs), and money market funds are positioned to offer slightly better returns. As commercial banks adjust to the new federal funds rate, consumers willing to shop around can secure attractive yields on their liquid savings, rewarding prudent fiscal habits after years of negative real returns during the early inflationary spike.
Official Statements and Industry Reactions
The decision has sparked widespread debate among economists, financial analysts, and policymakers regarding the delicate balance between curbing inflation and sustaining economic momentum.
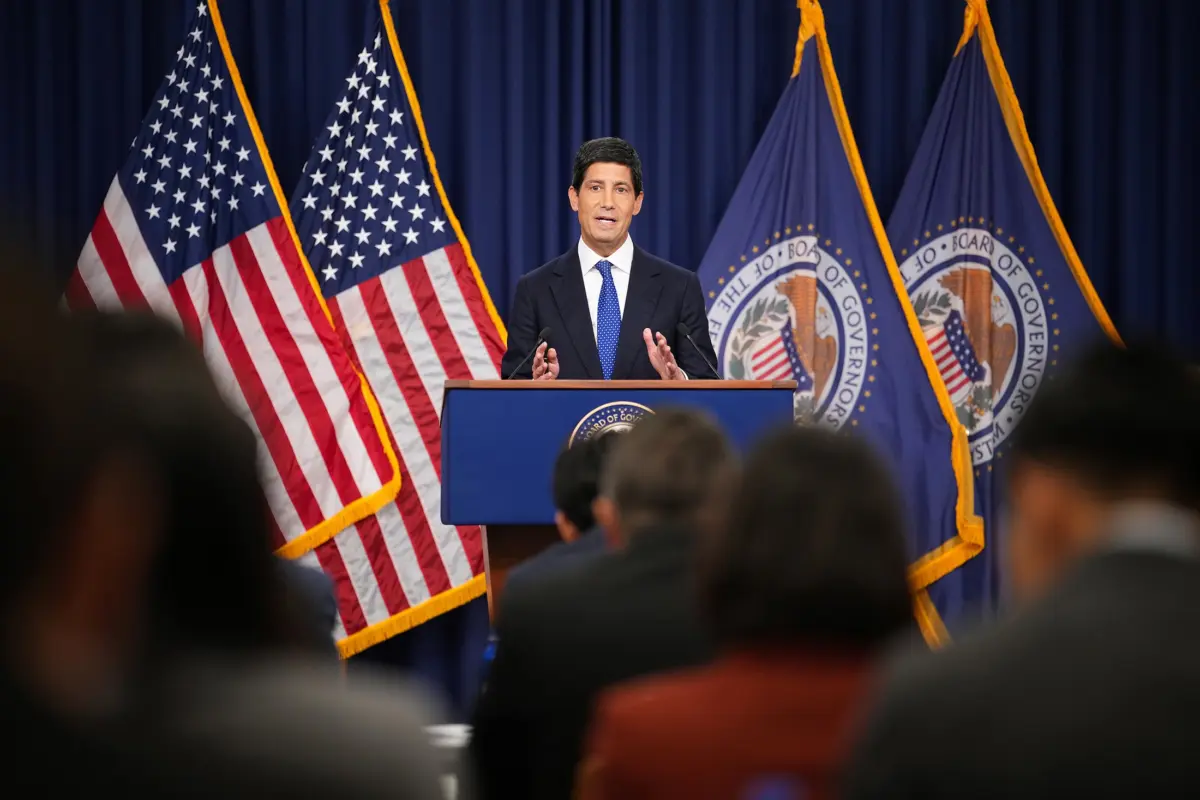
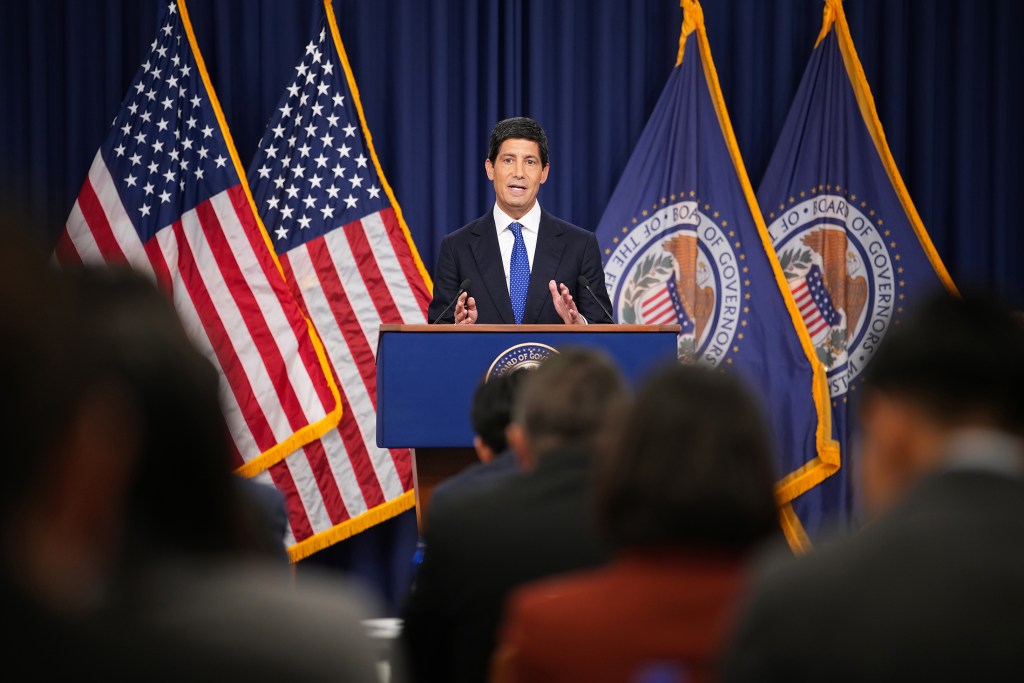
During the post-meeting press conference, Fed Chair Kevin Warsh defended the committee’s unanimous decision with blunt pragmatism.
"The plain fact is that inflation is too high and has been for too long," Warsh stated during his address, as reported by The New York Times. "While monetary policy operates with lags, we cannot simply wait indefinitely for normalization to happen on its own. Price stability is the bedrock of a healthy, sustainable economy, and we are committed to using our full toolkit to achieve it."
Industry experts have largely characterized the move as a necessary, albeit painful, course correction. Ted Rossman, principal consumer finance analyst at Money Management International, offered a candid assessment in an interview with The Washington Post:
"I know a rate hike may feel like bitter medicine, but we need it because we can’t just keep having this runaway price growth."
Other financial strategists note that the unanimous nature of the vote—with all 12 FOMC members aligning behind Warsh—demonstrates a unified institutional resolve. Unlike periods of past policy division, the central bank appears entirely synchronized in its assessment that the inflation threat warrants aggressive vigilance over passive accommodation.
Future Outlook: Navigating the New Economic Normal
As the dust settles from Wednesday’s historic announcement, economists and market participants are already looking ahead to the remainder of 2026 and into 2027. The central question facing the financial world is whether this quarter-point increase is an isolated adjustment or the opening salvo of a sustained tightening cycle.
Projections for Monetary Policy
Much will depend on upcoming employment reports, consumer spending metrics, and monthly Consumer Price Index (CPI) readings. If inflation proves sticky and refuses to trend toward the Fed’s 2% target, financial markets should price in the distinct possibility of subsequent rate hikes in upcoming FOMC meetings. Conversely, should economic growth show signs of sharp deceleration, the central bank may opt to pause once more to prevent inducing a severe recession.
Strategic Advice for Consumers and Businesses
- De-leveraging Variable Debt: Financial planners strongly advise consumers to prioritize paying down variable-rate debt, particularly credit cards and personal lines of credit, before further rate adjustments compound interest charges.
- Refinancing Considerations: Homeowners with adjustable-rate mortgages scheduled to reset in the near term should evaluate locking in fixed rates if market conditions permit, mitigating future exposure to rising benchmark rates.
- Optimizing Yields: Savers should audit their current depository institutions to ensure they are fully capitalizing on high-yield savings products, turning the high-rate environment to their advantage.
Ultimately, the Federal Reserve’s pivot on Wednesday signals the definitive close of an economic chapter. As consumers, businesses, and investors adjust to a 4% baseline benchmark rate, financial resilience and disciplined debt management will be paramount in navigating the road ahead.