
NEW YORK — In the rapidly evolving landscape of global commerce, marketing, and media, a foundational debate is quietly threatening to upend the traditional agency holding company. At the heart of the storm is a direct, unfiltered critique of the financial architectures that have sustained the advertising industry for decades.
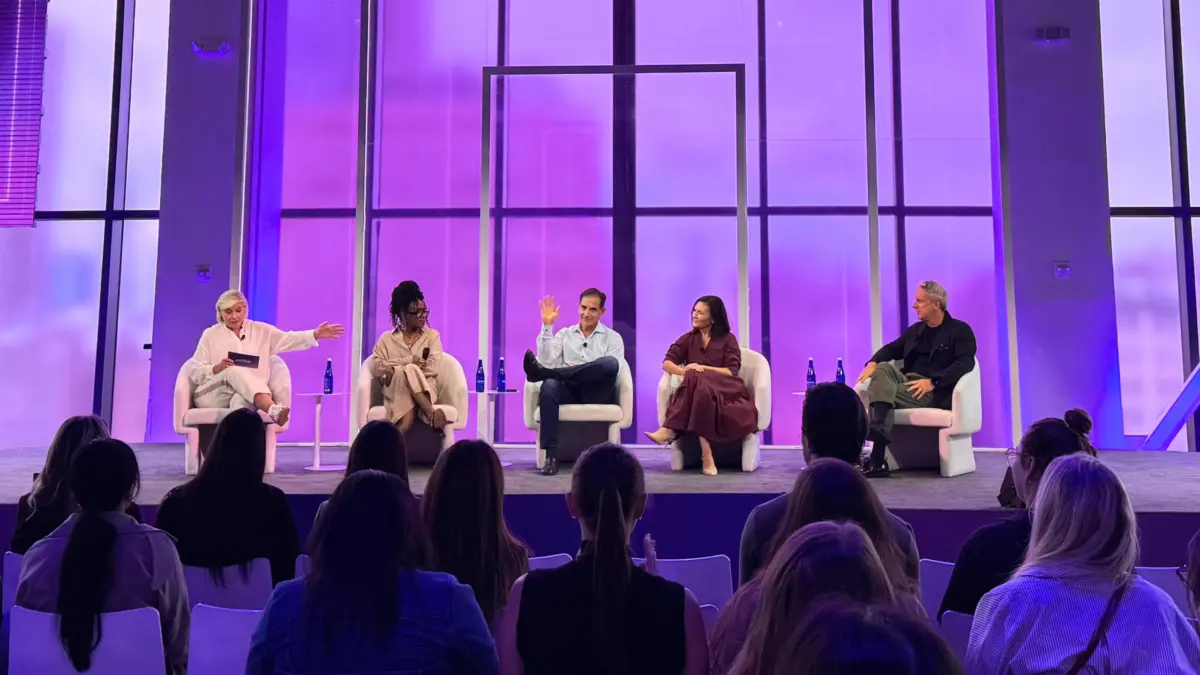
Speaking candidly on stage at Smartly’s Advance event in Lower Manhattan, Bob Lord, president of independent agency powerhouse Horizon Media Holdings, leveled a sharp condemnation against legacy labor-based pricing models and principal-based buying structures. According to Lord, these deeply entrenched financial mechanisms are no longer merely outdated—they are active anchors weighing down client growth in an era demanding agility, precision, and technological integration.
Lord’s critique cuts to the core of how major holding companies (“holdcos”) generate revenue, exposing a fundamental conflict of interest between legacy monetization strategies and modern enterprise needs. As agencies scramble to prove their value in a hyper-digitized marketplace dominated by artificial intelligence, automation, and real-time data, the industry finds itself locked in a tug-of-war between structural inertia and transformative necessity.
Executive Overview
The modern advertising ecosystem is undergoing a tectonic shift. For decades, the dominant economic engine of the agency world has been built on headcount—specifically, the Full-Time Equivalent (FTE) model—paired with principal-based media buying. Under this system, agencies scale their revenue by billing clients for the sheer volume of human hours deployed on an account, or by capitalizing on proprietary media inventory arbitrage.
However, as emerging technologies redefine productivity, the traditional equation is breaking down. When artificial intelligence and advanced automation can execute tasks in seconds that once required teams of analysts weeks to complete, the logic of billing strictly by the hour collapses.
Bob Lord’s recent remarks at the Smartly Advance event encapsulate a growing realization among forward-thinking industry leaders: the traditional agency business model is fundamentally misaligned with client outcomes. By tying revenue to labor rather than value, efficiency, or measurable business growth, legacy agencies are economically disincentivized from adopting the very technologies they claim to champion.
This in-depth report explores the anatomy of Lord’s critique, the mechanics of legacy agency pricing, the imperative for "composable architectures," and what this impending economic reckoning means for the future of the marketing services industry.
Detailed Chronology: The Evolution of Agency Pricing and the Breaking Point
To understand the gravity of Bob Lord’s statements, it is necessary to trace the historical evolution of agency compensation models and how the industry arrived at this critical juncture.
Phase 1: The Commission Era (Pre-1990s)
For the better part of the 20th century, the advertising agency business was defined by the standard 15% media commission. Agencies acted primarily as brokers, creating creative assets and securing placement in print, television, and radio, taking a standard cut of the total media spend. While simple, this model rewarded sheer volume: the more a client spent on media, the more the agency made, regardless of the campaign’s actual return on investment (ROI).
Phase 2: The Rise of the Fee and FTE Model (1990s–2010s)
As media fragmented with the advent of digital channels, cable television, and early internet advertising, the 15% commission model eroded. Brands demanded transparency and accountability, leading to the widespread adoption of fee-based compensation.
Chief among these was the Full-Time Equivalent (FTE) model. Agencies and clients would negotiate a fee based on the estimated number of human hours required to service an account, translated into dedicated headcount. While ostensibly more transparent than commissions, the FTE model inadvertently created a perverse incentive: it rewarded inefficiency. The more complex or bloated a staffing plan was, the more revenue the agency could extract from the client.
Phase 3: The Holdco Era and Principal-Based Buying (2010s–Present)
Concurrently, the industry consolidated into a handful of massive global holding companies. To offset margin pressures from aggressive procurement teams, these holding companies heavily invested in proprietary trading desks, data management platforms, and principal-based buying operations—where the agency acts as a principal, taking ownership of media inventory before reselling it to clients at a markup.
While these investments generated significant profits for holding companies, they created a new dilemma. Having sunk billions into proprietary technology infrastructure over the preceding five to ten years, holdcos faced immense pressure to amortize those costs and monetize those platforms, frequently bundling them into client contracts whether they were the best solution for the brand or not.
Phase 4: The Breaking Point (Present Day)
The friction point arrived in Lower Manhattan at Smartly’s Advance event. Bob Lord, leveraging his extensive background spanning digital media, corporate technology leadership, and independent agency operations, pulled back the curtain on this financial machinery. By explicitly calling out FTE models and principal-based buying as relics of self-serving corporate finance, Lord articulated what many brand CMOs have suspected for years: agency monetization strategies are frequently designed to feed the holding company’s balance sheet rather than accelerate client business growth.
Supporting Context & Metrics: The Economics of Inertia
To evaluate Lord’s assertions, one must examine the macroeconomic realities currently facing corporate marketing departments and agency networks alike.
The Technology Paradox
Over the past decade, major agency holding companies have poured billions of dollars into enterprise software, data infrastructure, and AI integration. Theoretically, these investments should streamline operations and drive unprecedented efficiencies for clients.
However, because traditional agency revenues are tethered to human labor hours, increased efficiency creates a paradoxical problem: efficiency destroys revenue. If an AI tool reduces the manpower needed to run a programmatic media campaign by 70%, a purely FTE-based agency stands to lose 70% of its billing capacity on that account. Consequently, legacy holding companies face a structural conflict: they must choose between passing efficiency savings onto their clients (and hurting their own top-line revenue) or maintaining bloated staffing structures to protect their financial targets.
The Rise of Composable Architectures
In response to this paradox, industry innovators are championing what Lord describes as "composable architectures."
Unlike monolithic, closed-loop agency ecosystems where a brand is forced to use an end-to-end suite of proprietary tools owned by a single holding company, a composable architecture allows brands to plug and play best-of-breed software, data providers, and agency partners dynamically. It is modular, flexible, and entirely centered around the specific operational needs of the enterprise.
Industry metrics underscore the urgency of this transition. According to recent marketing procurement studies, over 65% of enterprise CMOs are actively restructuring their agency rosters to favor modular, project-based, or value-based compensation models over traditional retainers. Brands are no longer willing to pay for agency headcount padding; they demand transparent, outcome-driven partnerships.
Official Statements and Industry Reaction
While Bob Lord was careful during his address to note that he was "not picking on anyone"—framing his critique instead as an objective assessment of "an economic equation"—his remarks sent immediate ripples through the advertising community.
"You have to create composable architectures to drive clients’ business growth," Lord stated emphatically on stage. "What’s holding us back? Inertia."
Elaborating on the mechanics of legacy holding companies, Lord laid bare the underlying financial pressures driving industry behavior:
"It’s the old system: FTE-based models, principal-based buying—how the holdcos make their money. You’ve made investments in technology over the last five years. You need to monetize that investment, and you’re going to force it on your clients."
The reaction from industry observers, independent agencies, and enterprise clients has been swift. Procurement specialists have praised the transparency, viewing Lord’s comments as a validation of long-held suspicions regarding opaque holding company markups and forced technology bundling.
Conversely, holding company defenders argue that integrated models provide unmatched scale, data security, and seamless global execution—benefits that require significant capital expenditure to maintain. However, even within traditional networks, private acknowledgments are growing that the old compensation playbooks are rapidly reaching their expiration date.
Future Outlook: Navigating the Post-FTE Landscape
As the advertising industry looks toward the horizon—highlighted by upcoming major industry forums such as the upcoming ADWEEK House: Advertising HQ convening in Midtown—the dialogue around agency compensation is shifting from a peripheral discussion to an existential imperative.
1. The Death of the Standard Retainer
The traditional multi-million-dollar annual retainer built entirely on FTE projections is steadily giving way to hybrid models. Future agency compensation will likely be bifurcated into two distinct streams:
- Strategic Advisory Fees: High-value intellectual capital and brand stewardship billed for strategic insight.
- Value- or Outcome-Based Incentives: Compensation tied directly to verified business outcomes, such as incremental revenue growth, customer lifetime value enhancement, or verified media efficiency gains.
2. The Independence Advantage
Independent agencies like Horizon Media are uniquely positioned to capitalize on this shift precisely because they lack legacy holding company debt structures, proprietary inventory obligations, and Wall Street pressure to constantly amortize internal software investments. Without a parent holding company demanding that they push proprietary tech stacks onto unwilling clients, independents can remain truly objective, assembling the best composable tech and talent stacks for each unique client brief.
3. The Imperative for Transparency
Trust in the agency-client relationship has historically been strained by opacity in media buying rebates, principal trading margins, and labor allocation. As brands face tightening economic conditions and heightened scrutiny from CFOs, transparency will no longer be a marketable differentiator—it will be the baseline requirement for survival. Agencies that cling to obfuscated pricing models and forced software bundling will find themselves systematically uninvited from modern client rosters.
Conclusion
Bob Lord’s critique at the Smartly Advance event was more than a passing observation; it was a diagnostic diagnosis of an industry at a crossroads. The friction between legacy financial models and modern technological capabilities cannot be sustained indefinitely.
As the marketing ecosystem matures into an era defined by composable architectures, artificial intelligence, and hyper-targeted consumer engagement, agencies must decide whether they will remain tethered to the sinking anchor of structural inertia or shed the models of the past to build a more transparent, accountable, and growth-oriented future. For brands navigating this complex transition, the message is clear: the future belongs to those who build architectures designed for client success, not holding company balance sheets.